 1 / 2
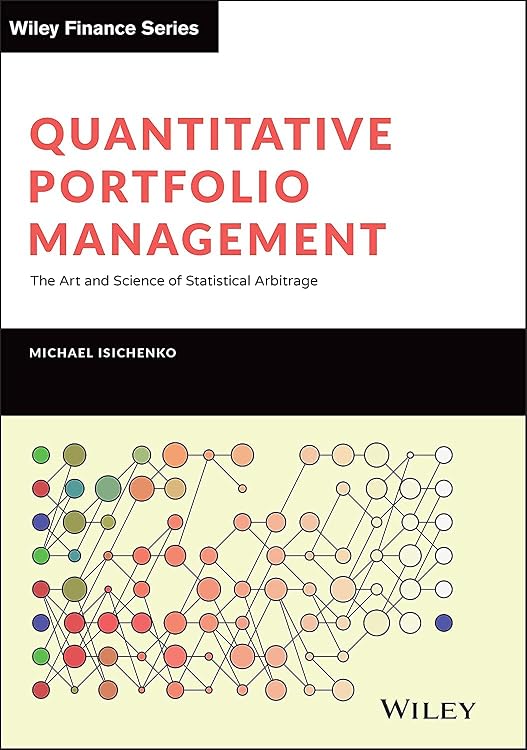
Quantitative Portfolio Management: The Art and Science of Statistical Arbitrage
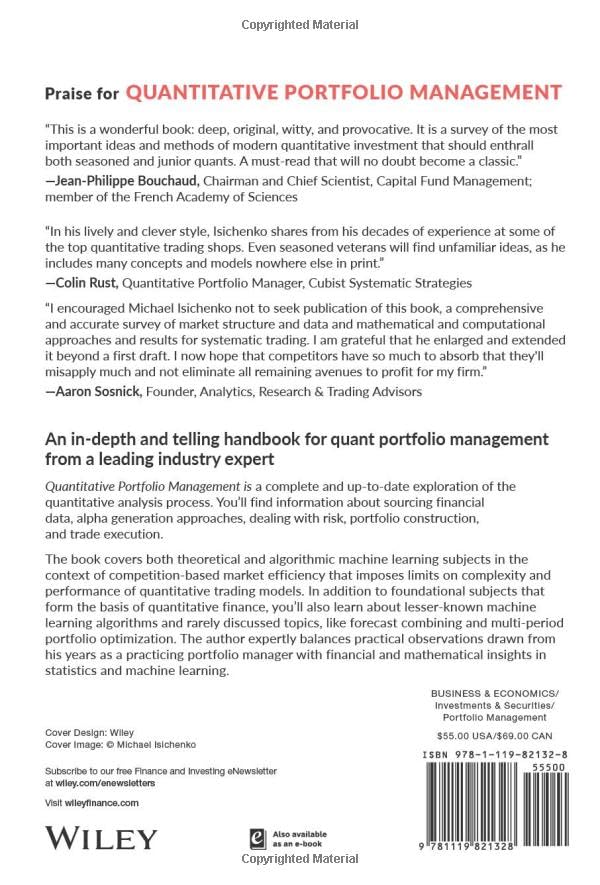
Quantitative Portfolio Management: The Art and Science of Statistical Arbitrage is a book on systematic equity trading, covering the path from financial data and return forecasts to portfolio construction and trade execution. Its stated scope includes machine learning, forecast combination, risk models and trading costs, though customer feedback is mixed on how deeply the material explains its subjects.
At a glance
- Explains a systematic workflow spanning financial data sourcing, return-pattern research, forecasts, portfolio risk and trade execution.
- Topics include machine-learning return forecasts, combining forecasts, overfitting, dimensionality, multi-factor risk models and trading costs.
- The listing positions it for quantitative trading and portfolio professionals, as well as data scientists and students in related disciplines.
Often bought together
Pros and cons
Pros
- The stated coverage links forecasting to portfolio construction and execution rather than treating stock prediction in isolation.
- Includes practical portfolio topics such as risk and trading costs alongside machine-learning methods.
Technical specifications
9 specifications| Publisher | Wiley |
|---|---|
| Publication date | 15 Nov. 2021 |
| Edition | 1st |
| Language | English |
| Print length | 304 pages |
| ISBN-10 | 1119821320 |
| ISBN-13 | 978-1119821328 |
| Weight listed | 612 g |
|---|---|
| Dimensions | 15.24 x 1.78 x 23.11 cm |
Who is it for?
A good fit for
- Quantitative traders and portfolio managers looking for a structured treatment of statistical arbitrage.
- Data scientists and students with a grounding in statistical or quantitative subjects who want to study financial applications.
Less suited to
- Readers looking for an introductory guide with clearly confirmed depth. Customer feedback is mixed on the book’s depth and reasoning.
Customer reviews on Amazon
- 5 stars
65% 65% - 4 stars
16% 16% - 3 stars
12% 12% - 2 stars
3% 3% - 1 star
4% 4%
Customer feedback is mixed on both the content and writing. Some customers appreciate the book, while others find its reasoning or depth lacking. The positive overall rating profile is encouraging but does not resolve that concern. Because the listed scope spans forecasting through portfolio construction, readers needing detailed explanations of each topic should weigh the mixed depth feedback.
Mixed feedback
- Customer feedback is divided on the content, with some liking it and others finding limited depth or reasoning.
- Feedback on the writing is mixed, including differing views on how deeply topics are explained.
Frequently asked questions
What subjects does the book cover?
The listing describes coverage of financial data, historical return patterns, machine-learning forecasts, forecast combination, portfolio risk and trade execution.
Who is this book aimed at?
Its stated audience includes quantitative traders, portfolio managers, data scientists and students in statistical and quantitative disciplines.
Do customers agree about the book’s depth?
No. Feedback is mixed: some customers like the content, while others say it lacks depth or reasoning. Consider this if you need a particularly detailed treatment.
Alternative options
A Practical Guide To Quantitative Finance Interviews
£20.73
Advances in Financial Machine Learning
£27.75
Inside the Black Box: A Simple Guide to Systematic Investing (Wiley Finance)
£24.71
Generative AI for Trading and Asset Management
£30.80